Mark Gongloff: Why your home insurance costs more than your property tax
Published in Op Eds
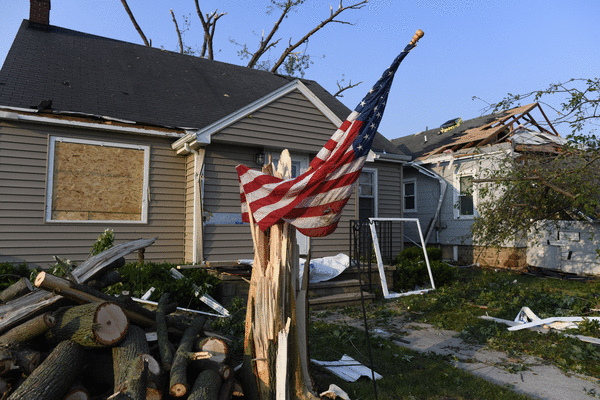
An annoying, persistent myth of climate discourse is the idea that trying to stop the planet from becoming a charred hellscape is antithetical to the affordability of life’s basic needs. Have you seen charred hellscapes? They tend to be short on the essentials, and shortages usually make things more expensive.
Consider housing. Home insurance is already ludicrously expensive in many parts of the country, and the soaring cost is putting this foundational material of Maslow’s pyramid even further out of reach for many Americans. And the main reason premiums have risen more than 46% since 2021, triple the rate of inflation, is the effect a changing climate is having on natural disasters. In housing, as in so many other basic needs, the environment directly influences affordability.
In fact, in two-thirds of U.S. counties, home-insurance premiums now cost more than property taxes, according to new research from Bloomberg Intelligence analyst Andrew John Stevenson. Throw in auto insurance against extreme-weather damage, and that gap stretches to 75% of U.S. counties. And unlike property taxes, homeowners can’t deduct insurance premiums from their income-tax bills. They just have to eat them.
On a county-by-county basis, the average of these “climate” premiums is $3,160 a year, compared with $2,423 for property taxes, Stevenson estimated. On a national level, property taxes are still higher, on average, at $4,594, but that reflects the impact of high-tax places such as California and New York. Insurance is a much bigger lift in low-tax, high-disaster areas such as the Deep South and the Plains, where premiums can cost four times more than property taxes.
And the more insurance puts housing out of reach and slows home sales, the more it threatens the property-tax base of these counties, resulting in either fewer government services or property-tax increases, or both.
Alabama, Colorado and Oklahoma aren’t as well-known for catastrophes as wildfire-prone California or hurricane-prone Florida. But a hotter planet is juicing the bad weather these places get, particularly thunderstorms that produce tornadoes, high winds and massive hailstones. These severe convective storms now generate more insured damage each year than any other disaster in the U.S., according to the Insurance Information Institute. Those losses rose from less than $10 billion in 2015 to $52 billion last year.
Meanwhile, deductibles are rising as insurers try to keep premiums from getting out of control. That means homeowners are paying an increasing share of whatever property damage they suffer, adding to their affordability woes. In some of the hardest-hit parts of the country, uninsured property losses can run to 5% of total county GDP or more, by Stevenson’s measure. The gap between how much people pay for home insurance and potential damages due to floods and wildfires alone could run to $2.7 trillion, by one estimate, enough to bother the entire housing market.
Policymakers worldwide seem to think affordability and climate stability are diametrically opposed in a zero-sum contest. For example, the typical government reaction to the rising fossil-fuel prices triggered by the Iran war has been to make it easier for people to buy more fossil fuels, greasing the skids with more than $1 trillion in government subsidies (on top of the $7 trillion a year they already enjoy).
This is not only environmentally unsound but economically dubious: Paying people to buy more of a scarce commodity certainly doesn’t make it less scarce. A better approach would be giving direct support to families that need it while hastening adoption of energy sources that can’t get stuck in the Strait of Hormuz and, as luck would have it, don’t heat the planet. Similarly, solving the insurance crisis must balance keeping housing affordable while also discouraging building and rebuilding in disaster zones.
Ditching the fossil fuels heating the planet would ultimately address many of these problems. But that transition can also be expensive in the short term and raise electricity bills, adding to that particular affordability crisis. Again, the all-too-common response, even in supposedly climate-friendly polities such as New York and Canada, is to spend more on fossil-fuel infrastructure and less on renewables.
This is mistaking the symptom for the disease. Access to shelter, water, food, energy and other needs is threatened when the environment grows dangerous. Making those things more affordable and accessible, like addressing the climate crisis, can be a political and logistical nightmare. But it would help to keep in mind that they’re one and the same problem.
_____
This column reflects the personal views of the author and does not necessarily reflect the opinion of the editorial board or Bloomberg LP and its owners.
Mark Gongloff is a Bloomberg Opinion editor and columnist covering climate change. He previously worked for Fortune.com, the Huffington Post and the Wall Street Journal.
_____
©2026 Bloomberg L.P. Visit bloomberg.com/opinion. Distributed by Tribune Content Agency, LLC.

Comments