Commentary: Universal public health insurance is the answer
Published in Op Eds
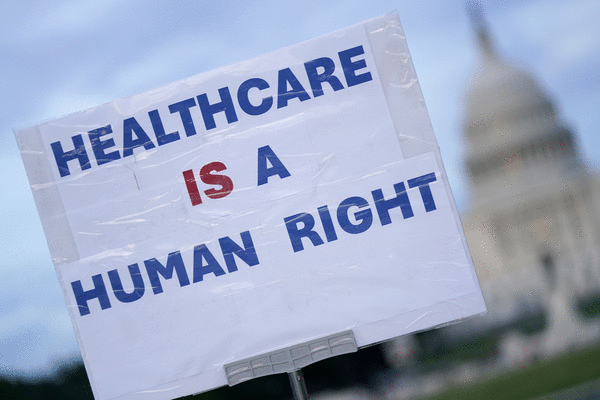
Employer-sponsored health insurance is rapidly deteriorating. In 2027, premiums are expected to see their largest single-year increase in two decades, jumping 11% and closing in on a nearly five-fold increase this century. The amount workers pay for their portion today would have covered the entire premium in 2000.
This coverage will never get more affordable, and it can only further distort the labor market through dampened wage growth, job lock and low levels of self-employment. If the next 25 years of premium increases are like the past 25, then employer premiums will be $120,000 in 2050.
All of which raises the question: Is there some combination of premium increases, medical debt, and coverage denial that galvanizes Americans to abandon this system? Maybe, maybe not. What Americans really need to do is embrace what’s next: universal public health insurance with private supplemental plans.
That may sound radical, but it’s not. Arguably, the U.S. has been preparing for this transition for six decades. Universal public health insurance isn’t hard to design, but it does require some tough choices: What is covered? Are there any out-of-pocket costs for users, and how are they structured? Are private supplemental plans allowed? If so, do they replace public coverage or top it up?
For these and other questions, Medicaid and Medicare often made different choices. Universal public health insurance wouldn’t be starting from scratch, but taking the lessons of the two existing programs to inform the design of a new, single form of public coverage. From this lens, Medicaid and Medicare are the 60-year experiment. There is now enough data to start building what’s next.
Again, it may sound expensive, but — expensive is a relative term. The Tax Foundation estimates that across Medicaid, Medicare, employer-sponsored health insurance tax subsidies and marketplace tax subsidies, federal health spending is $2.7 trillion, or 8.9% of GDP. All of those components are expected to increase at a fast clip over the next 10 years. A universal public health insurance plan is by no means free, but a way to streamline America’s already considerable health spending into a single program — no gaps, no overlapping and redundant administration, and much more price negotiation power.
From the public side, it’s pretty straightforward: All Americans would be enrolled into a new public health insurance plan via their Social Security number. No paperwork, plan options, enrollment windows or administrative penalties. Just covered. Doctors and hospitals, who are already used to billing the government, would continue to do so. Medicaid and Medicare would no longer exist.
The private side is messy, because the private health insurance industry would likely collapse were it not for the hundreds of billions of tax subsidies it receives every year. For all the free-market capitalists who would prefer a purely private system to a government one, the existing private system is the most heavily subsidized and government-dependent industry in the U.S. It’s not going to fly on its own wings.
At the same time, the private side would be necessary to provide supplemental coverage to the universal public plan. Amy Finkelstein and Liran Einav, two health economists who proposed universal public health insurance in their 2023 book We’ve Got You Covered, estimate that two-thirds of Americans would still want some kind of private plan. The new universal public health insurance system would need to give private insurers lead time to design those plans and clear expectations of what they can and cannot offer.
Once you get past the holdups that come with the transition, of whatever variety — whether its cost, public provision, employer bargaining advantage — the benefits of a new system stack up quickly. Without the profit motive, for example, the government’s insurance can cover care in rural areas that are rapidly losing providers. Medical debt, surprise bills, out-of-network charges, coverage gaps, and other pernicious fees of our private system would become things of the past.
And it’s impossible to overstate the enormous weight the end of employer coverage would lift from the labor market, especially for small businesses. A fully federal universal health insurance program would also relieve states of Medicaid spending, which accounts for a third of their budgets and could free up money for other purposes, such as education or housing.
Universal public health insurance with private supplement is the future; it is the logical answer to every hard question on cost, coverage, negotiation and market distortion. America will be fine. To use an analogy, think of next system like a flight from New York to LA: Public health insurance is a coach ticket. Supplemental coverage gets you a seat in first class. But everyone is going to get there.
____
This column reflects the personal views of the author and does not necessarily reflect the opinion of the editorial board or Bloomberg LP and its owners.
Kathryn Anne Edwards is a labor economist, independent policy consultant and co-host of the Optimist Economy podcast.
©2026 Bloomberg L.P. Visit bloomberg.com/opinion. Distributed by Tribune Content Agency, LLC.

Comments