Ask the Builder: Protecting your home from fire
I doubt you think much about your house burning down. Or, for that matter, any other traumatic event. You just want to look away and switch your mental gears. I admit I’m guilty of this behavior. I feel it’s very common.
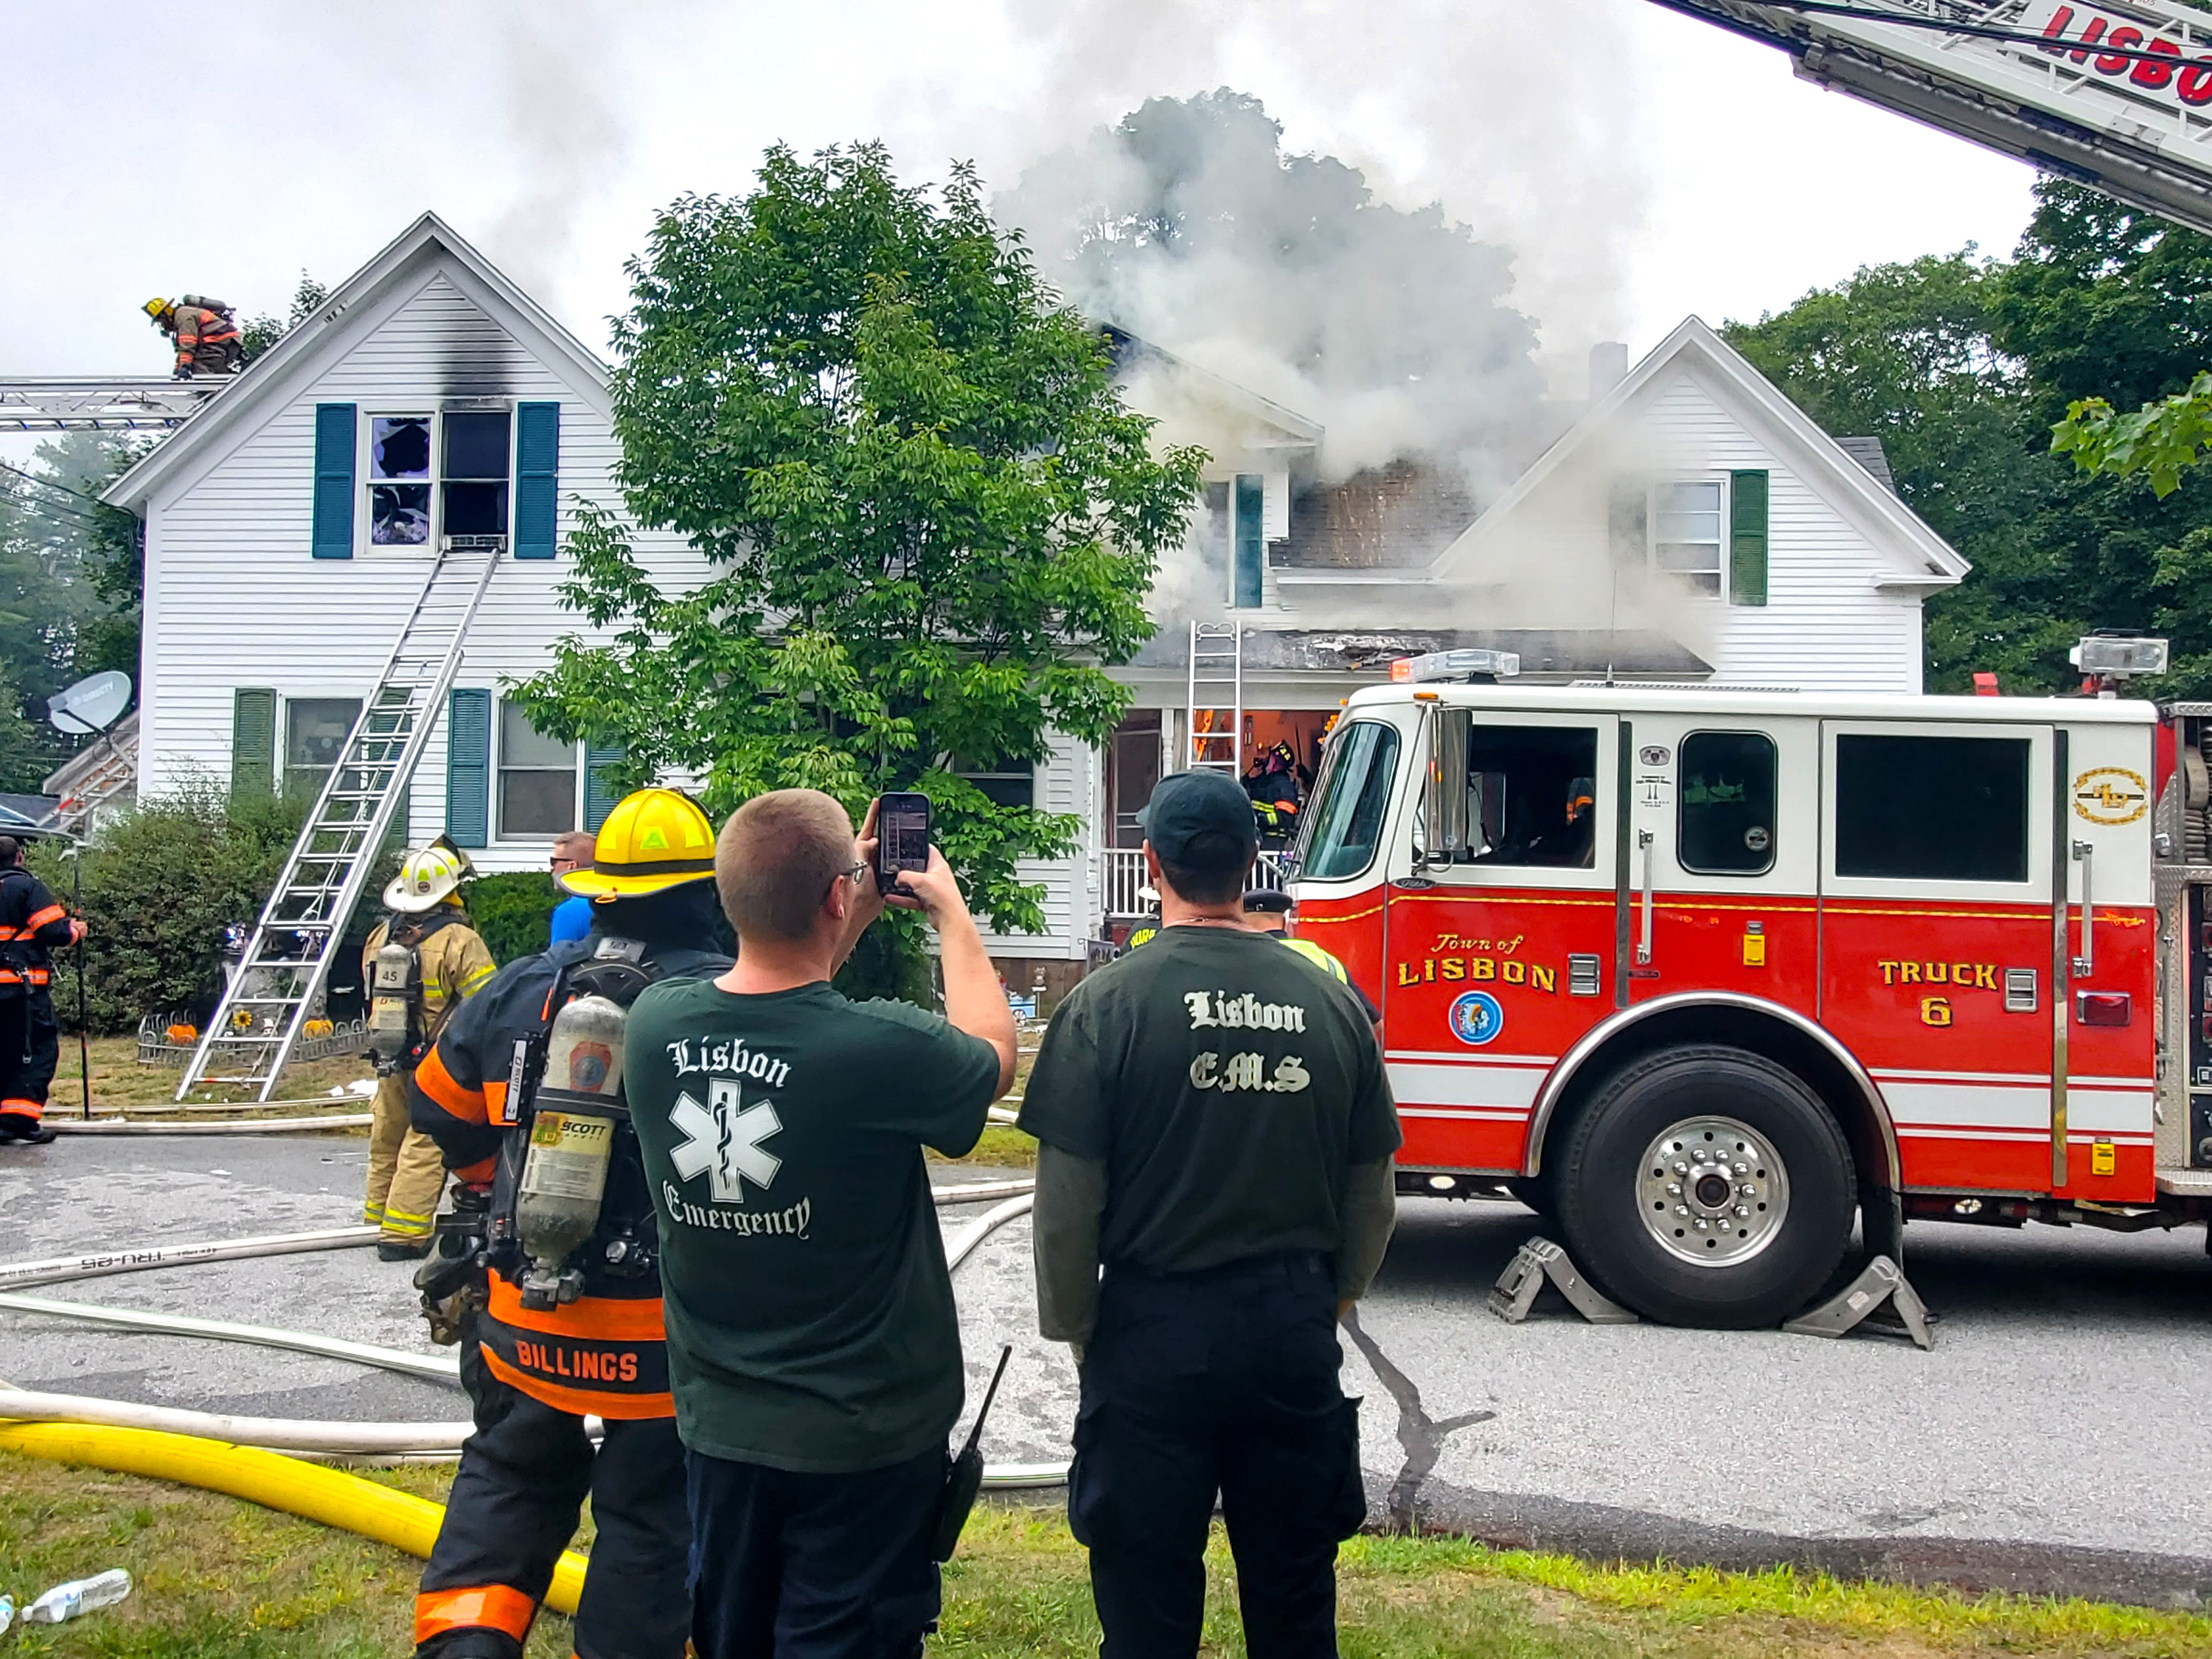
I’ve walked through houses that have been destroyed by fire. The destruction caused by the heat, smoke, and water used by the firefighters is enormous. Prized possessions can be reduced to ashes in minutes.
Here’s an example of how traumatic a house fire can be. Twenty-one months ago, my very good friend and his wife lost their home in Altadena, California, to the Eaton wildfire. They had just a few hours to evacuate. Their house, and just about everything in it, was consumed by the fire. Several holy cards owned by my friend’s wife somehow survived with singed edges. Talk about a miracle!
The house originally belonged to my friend’s wife. The loss of the house, and all of the things in it, caused her so much mental anguish she couldn’t handle visiting the lot for almost 18 months. My friend had to sift through the ashes and make visits to check on the reconstruction.
Decades ago, I found myself walking through a burned house to give a reconstruction bid. It was a cold day. The homeowner was bundled up in the basement trying to create an inventory of the things lost in the fire. He was unable to speak. His eyes were glazed over as he made entry after entry on a legal pad of the things he and his family lost. The mood was more somber than at a funeral.
This same scenario just played out in Spokane, Washington. Over 600 homes were consumed by a recent wildfire. I can assure you those who lost their homes are suffering. There’s a very good possibility some may never recover from the mental anguish. Believe me, it can be that bad.
What can you do now to minimize the misery caused by a house fire? I maintain the first thing you should do is get out your home insurance policy and read it. Take notes as you do this. You’ll discover a large list of things that aren’t covered in a loss. You’ll notice low limits on things that might be covered.
Not all policies are the same. Will your house be rebuilt to the same quality level? If you currently have Andersen windows and doors, will your insurance company give you the money to get the exact same ones? If your home has stunning solid red-oak hardwood floors, will you have the same when you rebuild? You must find out about this.
You need to understand your home insurance policy is nothing more than a contract. This means the insurance company is not going to do one extra thing for you outside of what’s stated in the contract. Their goal is to write a check to you that represents their exposure per the contract (policy). Never forget this.
You’ll discover while reading your policy that you have coverage for personal items such as clothes, furniture, tools, and everything you own that you have inside your home. You’ll have to prove you have them. The insurance company will not take your word.
It’s never been easier to document what you own. Doing this is like eating an elephant, and pachyderms are best eaten one bite at a time. You’ll use your smart phone’s video camera to create your inventory. You’ll do this one room or one dresser at a time. It may take you two or three months, but you’ll never regret doing it.
Your job is to record and talk about each thing in your home. Show each item in the video. Slowly pan over each of the items in your closet. Open every drawer and empty the contents showing how many sweaters, the types, etc. Record each pair of shoes. I know this sounds crazy, but talk to a person whose verbal claims have been rejected by a tough insurance adjuster. Think of all the tools and utensils in your kitchen!
Upload your videos to the cloud. Share the links to the videos with your insurance company. Document that you’ve done all this to avoid an argument with your insurance company.
I had a small water leak several years ago. Dealing with the insurance company adjuster was not pleasant. I discovered my insurance agent was of no use in helping negotiate with the insurance company. My frustration was relieved only after contacting the New Hampshire Insurance Department office. Within days of making contact with them, I had a check delivered to my front door by a FedEx driver.
My last piece of advice is for you to contact your local fire department. Find out if they have a fire prevention officer. If so, ask for that person to visit your home to do an inspection. This professional will point out all of the fire hazards you might be ignoring.
A year ago, a friend of mine sent me a photo of cardboard boxes stacked in front of her furnace. I called her immediately begging her to get them away from the furnace door where an errant flame might ignite the boxes. How many fire hazards are in your home? Find out now.
I’m available to answer any questions you have about my own insurance nightmare. Just use this link to set up a phone call: https://go.askthebuilder.com/coaching
Subscribe to Tim’s FREE newsletter at AsktheBuilder.com. Tim offers phone coaching calls if you get stuck during a DIY job. Go here: go.askthebuilder.com/coaching
©2026 Tim Carter. Distributed by Tribune Content Agency, LLC.

Comments